
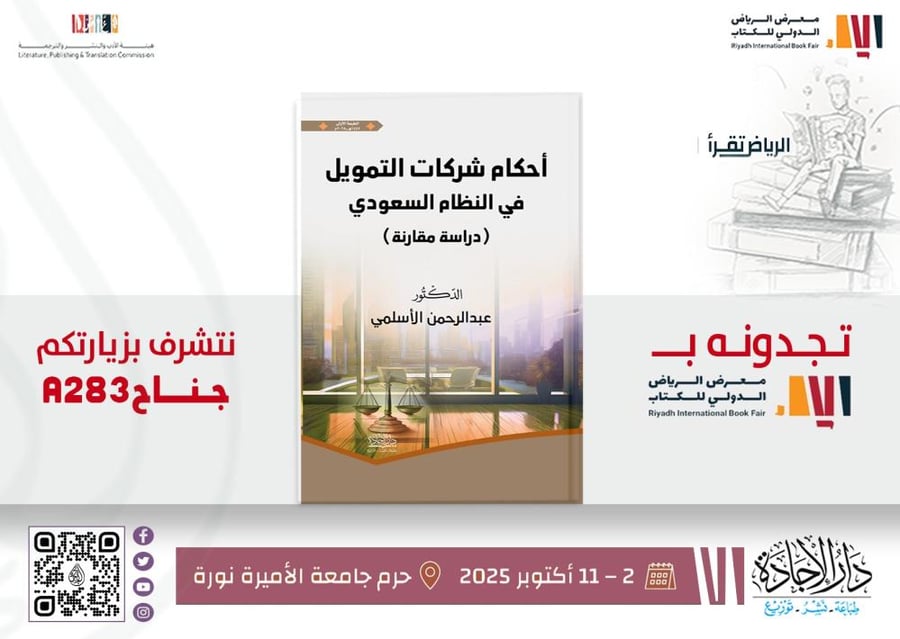
Financing companies' rulings in the Saudi system by Dr. Abdulrahman Al-Osaimi
100ر.س
Product description
Regulations of financing companies in the Kingdom of Saudi Arabia
Dr. Abdulrahman Al-Sulami
First edition 1447 AH
Number of pages: 742 pages
Book contents:
This research consists of an introduction, a preface, three chapters, a conclusion, and indexes.
The introduction includes: the importance of the topic and reasons for choosing it, research objectives, research problem, research questions, previous studies, research methodology, research plan.
The preface: the nature of financing companies, which includes three sections:
First section: definition of financing companies, with three demands.
Demand one: definition of companies.
Demand two: definition of financing.
Demand three: definition of financing companies.
Second section: characteristics of financing companies.
Third section: types of financing activities.
First chapter: procedures and rules for regulating financing companies, consisting of two sections.
First section: procedures for issuing a license to financing companies, with two demands.
Demand one: licensing requirements, including three points.
Point one: licensing application attachments.
Point two: suitability of founding members and board members.
Point three: minimum paid-up capital of the company.
Demand two: issuing a license to financing companies, with four points.
Point one: examination of the submitted application and decision.
Point two: scope and duration of the license.
Point three: termination of the license.
Point four: completing the procedures for establishing the financing company.
Second section: organizational structure of financing companies, with six demands.
Demand one: Board of Directors.
Demand two: committees derived from the Board of Directors.
Demand three: shareholders' rights, with two points.
Point one: receiving profits.
Point two: attending shareholders' meetings.
Demand four: internal regulatory rules for financing companies, with twelve points.
Point one: organizational structure, method of exercising powers, and responsibilities.
Point two: granting credit and operational procedures.
Point three: executive management.
Point four: financial and accounting management.
Point five: information technology and security.
Point six: customer service and collection.
Point seven: risk management.
Point eight: audit management, compliance, and internal control.
Point nine: salaries, bonuses, and incentives.
Point ten: errors and complaints.
Point eleven: combating fraud in financing companies.
Point twelve: changes in senior management.
Demand five: assigning special tasks to financing companies, with two points.
Point one: rules for assigning special tasks to financing companies.
Point two: tasks assigned to external service providers.
Demand six: supporting activities for financing activities, with two points.
Point one: issuing a license for supporting activities for financing.
Subsection one: scope and duration of the license.
Subsection two: cancellation and termination of the license.
Point two: rules for supporting activities for financing.
First chapter: regulations of financing, consisting of two sections.
First section: policies and stages of granting financing, with five demands.
Demand one: financing granting policies, with five points.
Point one: credit policy and its components.
Point two: credit analysis.
Point three: creditworthiness classification.
Point four: exposure limits and their provisions.
Subsection one: related parties.
Subsection two: obtaining financing that violates regulations.
Point five: maximum total financing.
Demand two: financing guarantees, with three points.
Point one: accepted types of guarantees.
Point two: basis for calculating the value of guarantees.
Subsection one: monitoring guarantees.
Subsection two: executing on guarantees.
Point three: risk provisions.
Demand three: stages of granting financing, with nine points.
Point one: consumer credit record.
Point two: examining the consumer credit record.
Point three: registering credit information of the beneficiary.
Point four: administrative levels for granting financing.
Point five: assessing the creditworthiness of the applicant and their ability to repay.
Point six: assessing exposure risks.
Point seven: evaluating guarantees.
Point eight: insurance against financing risks.
Point nine: refinancing.
Demand four: assets of financing and rights arising from them, with two points.
Point one: intended disposal of assets of financing or rights arising from them.
Point two: procedures for disposing of assets or rights.
Demand five: prohibitions for financing companies, with two points.
Point one: activities prohibited for financing companies.
Point two: facilities prohibited for financing companies.
Second section: protecting beneficiaries' rights, with three demands.
Demand one: principles of protecting clients of financing companies, with two points.
Point one: general principles.
Point two: mutual responsibilities.
Demand two: beneficiaries' rights related to the financing contract, with ten points.
Point one: contract data.
Point two: standards for financing costs and how to calculate them.
Point three: annual percentage rate.
Point four: fees, commissions, and administrative costs.
Point five: effects of late installment payments.
Point six: exercising the right of withdrawal.
Point seven: early repayment.
Point eight: it is the financing contract.
Point nine: transfer of rights by the financing company to another party.
Demand three: general rights of beneficiaries, with five points.
Point one: data and information protection.
Point two: communication through advertising and marketing.
Point three: before or upon signing the financing agreement.
Point five: errors and complaints.
Third chapter: violations, penalties, and judicial jurisdiction, consisting of two sections.
First section: violations and penalties, with two demands.
Demand one: types of violations of the supervision system for financing companies and its executive regulations, with four points.
Point one: professional violations.
Point two: dealings that expose shareholders and creditors of financing companies to risk.
Point three: violation of the financing companies system and its regulations.
Point four: exemption of financing companies from some provisions of the executive regulation.
Demand two: penalties, with five points.
Point one: penalty for professional violations.
Point two: penalty for dealings that expose shareholders and creditors to risk.
Point three: penalty for delaying the debtor in fulfilling their debt.
Point four: penalty for continuing violations.
Point five: penalty for violating the supervision system for financing and its regulations.
Second section: judicial jurisdiction in disputes and violations arising from financing systems, with two demands.
Demand one: jurisdiction of the Dispute Resolution Committee for disputes and violations arising from financing systems, with four points.
Point one: international jurisdiction.
Point two: jurisdiction of the court of competent authority.
Point three: subject matter jurisdiction.
Point four: territorial jurisdiction.
Demand two: Dispute Resolution Committee for disputes and violations arising from financing systems, with two points.
Point one: rules of work for the Dispute Resolution Committee for disputes and violations arising from financing systems.
Point two: rules of work for the appellate Dispute Resolution Committee for disputes and violations arising from financing systems.
The conclusion: includes the most important results and recommendations.
Indexes include the following:
- Index of Quranic verses.
- Index of Hadiths and sayings.
- Index of names.
- Index of sources and references.
- Index of topics.

From Riyadh
Questions you might have